Florida Title Insurance Calculator
This Florida title insurance calculator works out the owner's and lender's premiums for a Florida closing. It also adds the state taxes and county recording fees that sit beside them on your settlement statement. Enter a price and a loan amount, then pick the county. The numbers update as you type.
Florida sets title premiums by rule, so every licensed agent charges the same rate for the same policy. Statutes fix the taxes as well. That makes most of the math predictable. The only real unknowns are the fees a title company sets for its own work, and we cover those further down.
Estimate your Florida closing costs
| Item | Amount | Usually paid by |
|---|---|---|
| Owner's title insurance policyPromulgated rate. Who pays is local custom and negotiable. | $2,075.00 | Seller, negotiable |
| Lender's policy (simultaneous issue)$25 when the loan does not exceed the price. | $25.00 | Buyer, negotiable |
| Documentary stamps on the deed70 cents per $100. | $2,800.00 | Seller, negotiable |
| Recording the deed (about 3 pages) | $27.00 | Buyer, negotiable |
| Documentary stamps on the note35 cents per $100. | $1,120.00 | Buyer, negotiable |
| Intangible tax on the mortgage0.2% of the loan. | $640.00 | Buyer, negotiable |
| Recording the mortgage (about 15 pages) | $129.00 | Buyer, negotiable |
| Estimated total | $6,816.00 |
How does this Florida title insurance calculator work?
It runs the same arithmetic a closing agent runs, just faster. First, it prices the owner's policy on the purchase price with the promulgated rate table. Then it adds the lender's policy. On a purchase with a loan, Florida lets the agent issue both policies together. So the lender's policy costs $25 as long as the loan does not exceed the price.
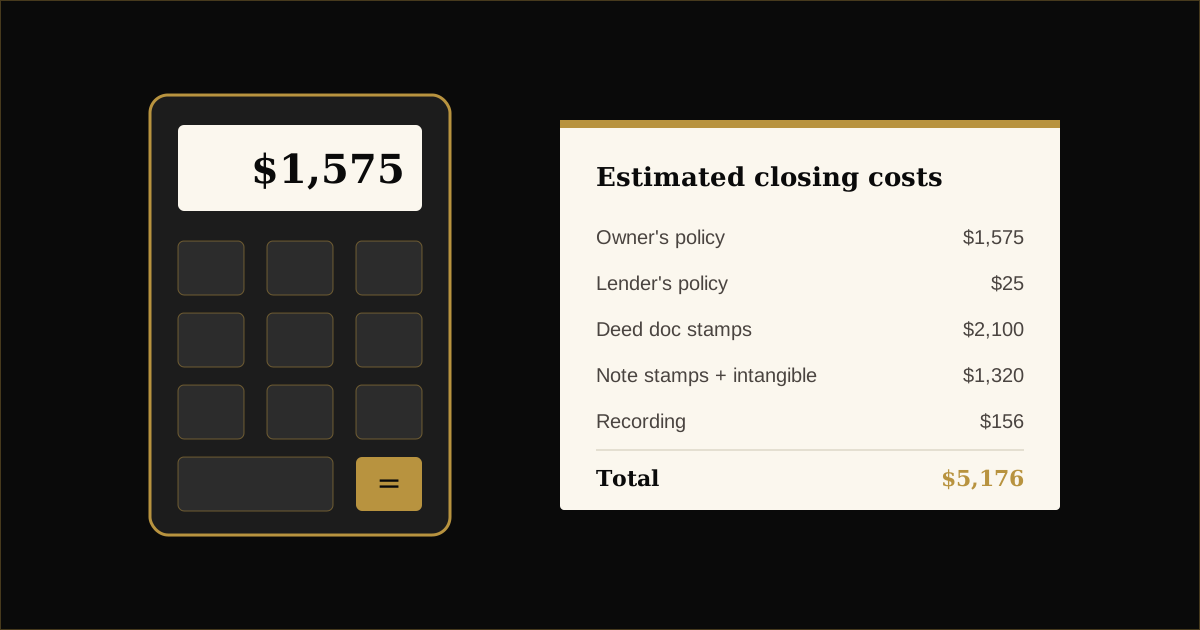
Next come the taxes. The calculator applies documentary stamps to the deed and to the note. After that it adds the intangible tax on the new mortgage. Finally, it estimates what the clerk charges to record the deed and the mortgage. Each line also shows who usually pays it.
For a refinance, the math changes. There is no deed and no owner's policy. Instead, the tool prices a lender's policy on the new loan. If you bought the home with an owner's policy, you may qualify for the lower reissue rate. Enter the amount of that old policy and the calculator applies the credit for you.
How much is title insurance in Florida?
Title insurance in Florida costs $5.75 per $1,000 of coverage on the first $100,000. Then it costs $5.00 per $1,000 up to $1 million. Above that, the rate keeps stepping down. The rates come from Rule 69O-186.003 of the Florida Administrative Code, and no agent may charge more or less than the rule allows.
| Coverage band | Rate per $1,000 | Cost of the full band |
|---|---|---|
| Up to $100,000 | $5.75 | $575 |
| $100,001 to $1,000,000 | $5.00 | $4,500 |
| $1,000,001 to $5,000,000 | $2.50 | $10,000 |
| $5,000,001 to $10,000,000 | $2.25 | $11,250 |
| Over $10,000,000 | $2.00 | Per $1,000 above |
So a $300,000 home works out like this. The first $100,000 costs $575. The next $200,000 costs $1,000. Add them and the owner's policy comes to $1,575. The minimum premium is $100, but that only matters on very small policies.
| Price or coverage | Owner's premium |
|---|---|
| $150,000 | $825 |
| $250,000 | $1,325 |
| $300,000 | $1,575 |
| $400,000 | $2,075 |
| $500,000 | $2,575 |
| $750,000 | $3,825 |
| $1,000,000 | $5,075 |
| $2,000,000 | $7,575 |
A lender's policy on its own uses the same table. That is why a cash buyer and a financed buyer pay almost the same total premium. The financed buyer adds only the $25 charge, unless the loan is larger than the price. In that case the extra loan amount prices at the full rate.
Want to know what the policy actually protects? Read our guide to what title insurance is, and then decide whether you need an owner's policy in Florida.
What is the Florida reissue rate, and who qualifies?
The reissue rate is a discount for property that already has recent title coverage. It drops the rate to $3.30 per $1,000 on the first $100,000. Above that, it charges $3.00 per $1,000 up to $1 million. However, the discount reaches only as far as the amount of the old policy. Any coverage above that amount goes back to the full rate.
| Coverage band | Rate per $1,000 | Cost of the full band |
|---|---|---|
| Up to $100,000 | $3.30 | $330 |
| $100,001 to $1,000,000 | $3.00 | $2,700 |
| $1,000,001 to $10,000,000 | $2.00 | $18,000 |
| Over $10,000,000 | $1.50 | Per $1,000 above |
On a purchase, the seller's owner's policy has to be less than three years old. A refinance works a little differently. If you hold an original owner's policy, your new lender's policy can get the reissue rate no matter how old your policy is. In both cases the agent and the underwriter must keep a copy of the prior policy. So dig yours out of the closing folder before you call.
Here is a real example. Say the seller bought two years ago with a $350,000 owner's policy, and you now pay $400,000. The first $350,000 prices at reissue rates, which comes to $1,080. The last $50,000 prices at the full rate of $5.00 per $1,000, which adds $250. As a result, the premium drops from $2,075 to $1,330. That saves $745.
Refinancing has one more option. Florida also has a substitution loan rate for a borrower who replaces a loan that a title insurer already covered. It charges a share of the full rate based on the age of the old loan. Your closing agent should check both rates and use the lower one. Still, the calculator shows only the reissue figure, so treat it as a ceiling.
How much are documentary stamps and intangible tax in Florida?
Florida taxes both the deed and the loan. Documentary stamps on a deed cost 70 cents per $100 of the price under section 201.02 of the Florida Statutes. The tax treats any part of $100 as a full $100. So a $300,050 sale pays on 3,001 units. On a $400,000 sale the deed stamps come to $2,800.
Miami-Dade is the exception. There, the deed rate drops to 60 cents per $100. But the county adds a surtax of 45 cents per $100 on any deed that does not convey only a single-family home, under section 201.031. A condo unit counts as a single-family home for this rule. So a $400,000 condo pays $2,400, while a $400,000 duplex pays $4,200.
The loan side carries two taxes. First, documentary stamps on the note cost 35 cents per $100 under section 201.08. Second, the intangible tax on the mortgage is 2 mills, or 0.2% of the loan, under section 199.133. On a $320,000 loan that means $1,120 in stamps and $640 in tax. The Florida Department of Revenue publishes the same rates and the same rounding rule.
| Tax or fee | Rate | Usually paid by | Example |
|---|---|---|---|
| Deed stamps, most counties | $0.70 per $100 | Seller | $2,800 |
| Deed stamps, Miami-Dade | $0.60 per $100 | Seller | $2,400 |
| Miami-Dade surtax, other property | $0.45 per $100 | Seller | $1,800 |
| Stamps on the note | $0.35 per $100 | Buyer | $1,120 |
| Intangible tax | 0.2% of the loan | Buyer | $640 |
| Recording, deed and mortgage | $10 first page, $8.50 after | Buyer | $156 |
A refinance pays the note stamps and the intangible tax again on the new loan. A cash purchase skips both, since there is no mortgage to tax. One exception is worth asking about, though. If you renew a note with the same lender and take no new money, section 201.09 can exempt the renewal from fresh stamps.
What does the county clerk charge to record a deed and mortgage?
Recording fees are small, but they add up. Under section 28.24, the clerk charges $10 for the first page and $8.50 for each page after it. That total combines a base fee with two statewide surcharges. A three-page deed costs $27 to record. A 15-page mortgage costs $129.
Page counts vary from file to file. A mortgage with a condo rider can run past 20 pages, while a short warranty deed may fit on two. For that reason the calculator assumes 3 pages for the deed and 15 for the mortgage. Your closing agent counts the real pages before closing day, so expect a small change here.
Who pays for title insurance and closing costs in Florida?
Custom decides most of it, and the contract can change any of it. In most Florida counties the seller buys the owner's policy and also picks the title company. However, in Miami-Dade, Broward, Sarasota and Collier the buyer usually pays for the owner's policy instead. The calculator flips the payer when you pick one of those four counties.
The seller also pays the deed stamps in nearly every deal. Meanwhile, the buyer covers everything tied to the loan. That means the lender's policy plus the taxes on the note and mortgage. It also means the fees to record the deed and the mortgage.
| Cost | Customary payer | Negotiable? |
|---|---|---|
| Owner's policy | Seller in most counties; buyer in Miami-Dade, Broward, Sarasota and Collier | Yes |
| Lender's policy | Buyer | Yes |
| Deed stamps | Seller | Yes |
| Note stamps and intangible tax | Buyer | Yes |
| Recording fees | Buyer | Yes |
Every one of these costs is negotiable. The standard Florida purchase contract lets the parties choose who pays for the owner's policy, and buyers and sellers trade these costs all the time. For the local picture, our county title guides cover custom in each of the 67 counties.
What does this estimate leave out?
The calculator covers the regulated costs. It does not cover the fees each title company sets for its own work. Those include the title search and the settlement fee, plus any lien or estoppel search. On a typical home sale they run $500 to $1,000 together. Our breakdown of title fees in Florida walks through each one.
Endorsements also add cost. Lenders usually ask for a few, such as a survey or condo endorsement, and the rate rules price each one on its own. Then there are costs that have nothing to do with title. For example, lender fees and prepaid interest show up on the closing disclosure too. So do property taxes and HOA dues.
Treat the result as a floor for the title and tax portion, not a final number. For a written figure on your deal, order title online or contact our office. You can also see everything we handle on our title services page.
Why use a Florida title insurance calculator before you sign?
Because many closing costs land on the buyer or seller by custom rather than by law. And custom can be negotiated. Knowing the numbers before you sign gives you something to trade. For example, a Palm Beach seller who expects to pay a $2,075 owner's policy might offer that as a credit instead of a price cut.
It also helps you catch mistakes. Premiums are fixed, so if a quote shows a higher owner's premium than the Florida title insurance calculator does, ask why. Usually the gap comes from an endorsement or a fee with a similar name. Now and then it turns out to be an error, and it is far cheaper to catch that early than at the closing table.
Florida title insurance calculator FAQ
Is title insurance the same price at every Florida title company?
Yes for the premium. Florida promulgates the rate, so every licensed agent charges the same amount for the same policy. Companies differ on their search and closing fees, which the rate rule does not set.
How much is title insurance on a $300,000 home in Florida?
The owner's policy costs $1,575 at the promulgated rate. If you also have a loan of $300,000 or less, the lender's policy adds just $25 when both policies issue together.
Who pays for the owner's title policy in Florida?
The seller pays in most counties. In Miami-Dade, Broward, Sarasota and Collier the buyer usually pays. Either way, the contract decides, so you can negotiate it.
How much are doc stamps on a $400,000 house in Florida?
Deed stamps come to $2,800 at 70 cents per $100. In Miami-Dade the deed rate is 60 cents, so a single-family home there pays $2,400. Other Miami-Dade property also owes the 45-cent surtax.
Do I pay for title insurance again when I refinance?
You buy a new lender's policy for the new loan. However, if you hold an owner's policy on the home, the reissue rate can cut that premium. You also pay note stamps and intangible tax on the new loan.
Is this calculator a quote?
No. It gives an estimate based on the published rates and typical page counts. Your title commitment and closing disclosure carry the final figures.
Ready for a real quote on your closing?
Send us the contract and we will open the file the same day. Then you get a title commitment and a closing figure you can rely on. You can also call (561) 810-2692 and talk to a coordinator in our Lake Worth office.